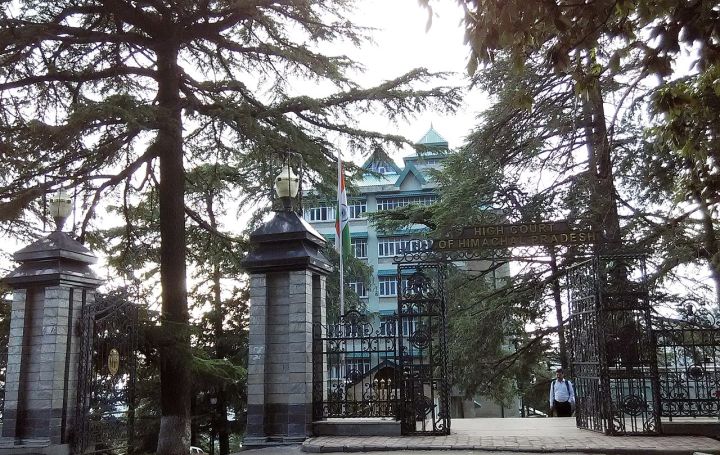
📷 Image: Wikimedia Commons / Sumita Roy Dutta
Business
HP High Court says bank's COVID-19 moratorium extension cannot bypass RBI NPA rules
✍️ Live Law
🗓 12 Oct 2026, 06:03 PM
👁 10
The Himachal Pradesh High Court ruled that a bank’s extension of the COVID-19 loan moratorium cannot override the Reserve Bank of India’s guidelines on classifying loans as non-performing assets.
The Himachal Pradesh High Court has held that a bank’s decision to prolong the COVID-19 loan moratorium does not exempt it from complying with the Reserve Bank of India’s norms on non‑performing assets (NPA). In its judgment, the bench clarified that regulatory guidelines on loan classification remain binding irrespective of temporary relief measures granted to borrowers.
RBI’s framework requires banks to classify a loan as an NPA when principal or interest payments are overdue for more than 90 days. The court observed that extending the moratorium cannot alter this statutory threshold, and banks must continue to assess and record NPAs in line with the central bank’s directives.
The ruling underscores that while moratoriums provide short‑term breathing space to stressed borrowers, they do not shield banks from regulatory compliance. Financial institutions will need to reflect any overdue amounts in their NPA accounts once the moratorium period ends, ensuring transparency in the banking sector’s health.
Industry observers note that the decision may prompt banks to review their credit monitoring practices and communicate clearly with customers about the impact of moratorium extensions on loan classification.